Best Health Insurance for Self-Employed in Arizona (2026 Guide)
Being your own boss in Arizona is great, until you need to see a doctor. No employer means no employer health plan. You have to find your own coverage. That can feel confusing fast.
The good news: Arizona actually has a lot of options in 2026. The tricky part is picking the right one for your income, your health needs, and your budget.
Quick answer: For most self-employed Arizonans, 1099 Health Insurance is the top choice. Here’s why. They are a Phoenix-based agency built just for self-employed workers, 1099 contractors, and small business owners. They shop both ACA marketplace plans and private plans for you, not just one company’s plans. They have close to 200 five-star reviews and have helped thousands of people find real, affordable coverage. This guide walks through your actual options, what they cost in 2026, and how to pick the right one.
Words to Know
A few terms come up a lot in this guide. Here’s what they mean, in plain words:
| Word | What It Means |
|---|---|
| ACA marketplace | The official place to shop for health plans, run by the federal government. |
| Premium | The amount you pay each month for your plan. |
| Subsidy (premium tax credit) | Money from the government that lowers your monthly premium, based on income. |
| Deductible | The amount you pay out of pocket before your plan starts paying its share. |
| Broker or agent | A licensed person who helps you compare plans, at no cost to you. |
Why It’s Harder for Self-Employed Arizonans to Get Coverage
If you work for a company, health insurance is often part of the deal. If you’re self-employed, that safety net is gone. You’re on your own to find a plan.
This is a big deal in Arizona. The state had at least 527,000 self-employed workers in 2023. That’s up nearly 13% from just a few years before. This comes from the Arizona Center for Economic Progress. Small business owners and self-employed workers make up a big share of the ACA marketplace, too. In a recent year, they were 1 out of every 4 people enrolled in Arizona’s marketplace.
In short: you are far from alone. But you do need to shop smart, because your options and your costs work differently than they do for a regular employee.
Your Health Insurance Options in Arizona
Here’s what’s actually available to you in 2026:
ACA Marketplace Plans
These are plans sold through HealthCare.gov. Arizona doesn’t run its own separate exchange, so everyone shops through the federal site. Seven companies offer 2026 marketplace plans in Arizona. This is based on data from HealthInsurance.org:
- Blue Cross Blue Shield of Arizona
- Cigna Healthcare of Arizona
- Health Net of Arizona
- Imperial Insurance
- Oscar Health Plan
- UnitedHealthcare of Arizona
- Antidote Health Plan of Arizona
These plans cannot turn you down for a health condition. Depending on your income, you may also qualify for a subsidy that lowers your monthly bill.
Private (Off-Exchange) Plans
The same kinds of plans are sometimes sold directly by an insurance company, outside the marketplace. The coverage rules are the same. But there’s one big difference. You can’t get a subsidy this way. So it’s usually a better deal only for people who earn too much to qualify for a subsidy anyway.
Short-Term Health Insurance
This is a lower-cost option for a short gap in coverage, like between jobs. It won’t cover a pre-existing condition, and it’s not meant to be permanent. Learn more about short-term health insurance options here.
Small Business Group Plans
Do you have even one or two employees? You may qualify for a small group health plan instead of an individual one. This can sometimes offer better rates. You can get a group health quote to compare.
Comparing Your Options at a Glance
| Plan Type | Can Include a Subsidy? | Covers Pre-Existing Conditions? | Best For |
|---|---|---|---|
| ACA marketplace | Yes | Yes | Most self-employed workers |
| Private (off-exchange) | No | Yes | Higher earners who won’t get a subsidy anyway |
| Short-term | No | No | A short gap in coverage, like between jobs |
| Small business group | Sometimes | Yes | Business owners with employees |
What Does Health Insurance Cost for Self-Employed People in Arizona in 2026?
This is the part everyone wants to know. The honest answer: it depends a lot on your income, since 2026 brought a big change.
Here’s what’s true right now:
- The average Arizona marketplace premium, after subsidies, is about $229 a month in 2026.
- That’s more than double the 2025 average of $113 a month.
- About 83% of Arizona enrollees still qualify for some subsidy.
- Before any subsidy, the average Arizona rate went up about 46% for 2026.
Why the jump? Extra federal subsidy help, in place since 2021, expired at the end of 2025. Congress did not extend it. That means people who earn more than about 400% of the federal poverty level lost their subsidy completely. People below that line still get help, just less of it than before.
Here’s a real example. It comes from the Arizona Center for Economic Progress. A 60-year-old married couple runs a small business in Arizona. They earn $82,000 a year. Without the extra subsidy, their premium could jump by $13,927 a year.
The takeaway: your actual cost depends completely on your specific income and age. Guessing isn’t a good plan. Getting a real quote is.
Two Tax Breaks Worth Knowing About
The self-employed health insurance deduction. If you’re self-employed, you may be able to deduct your health insurance premiums on your taxes. This can lower what you owe the IRS. The rules are laid out in IRS Publication 535.
A Health Savings Account (HSA). Some ACA marketplace plans count as a “high-deductible health plan.” If yours does, you may be able to open an HSA. The rules come from IRS Publication 969. Money you put in is tax-free. Money you take out for medical costs is also tax-free. It’s one of the few accounts that works this way.
Neither of these is tax advice, and the exact rules depend on your situation. A CPA or tax preparer can confirm exactly what you qualify for.
Common Mistakes Self-Employed Arizonans Make
- Picking a plan based on price alone. A cheap premium with a huge deductible can cost more overall if you actually need care.
- Assuming they don’t qualify for a subsidy. Many self-employed people still do, even with 2026’s changes. It’s worth checking before you assume.
- Forgetting to update their income estimate. Self-employed income changes throughout the year. An old estimate can throw off your subsidy amount.
- Waiting until open enrollment to compare options. A qualifying life event, like starting a business, can open a Special Enrollment Period any time of year.
- Going without coverage entirely to save money. A single emergency room visit can cost more than a year of premiums. Our guide on what happens if you don’t pay medical bills shows what’s really at stake.
Why 1099 Health Insurance Is the Top Choice for Self-Employed Arizonans
There are a lot of ways to shop for health insurance. Here’s what makes 1099 Health Insurance stand out for people in Arizona:
- They only work with self-employed people, 1099 workers, and small businesses. This isn’t a side focus. It’s the whole business.
- They shop more than one type of plan. Most agents only sell ACA marketplace plans. Or they only sell private plans. 1099 Health Insurance compares ACA marketplace options, private plans, short-term coverage, and HealthShare plans side by side. You see the full picture, not just one slice of it.
- They’re local. The team is based right in Phoenix, and works with clients across Arizona and other states.
- Real people trust them. They have close to 200 five-star reviews. You can read the Google reviews yourself.
- They’ve helped thousands of people find coverage that actually fits their budget, not just the first plan they saw.
- It costs you nothing to use them. Licensed brokers are typically paid by the insurance company, not by you, so getting help comparing plans doesn’t add to your bill.
- They cover more than health insurance. Once you have a health plan, you can also add dental, vision, and other supplemental coverage through the same agency.
If you want to see your real options instead of guessing, you can get a free quote in a few minutes.
Local, With Real People Behind It
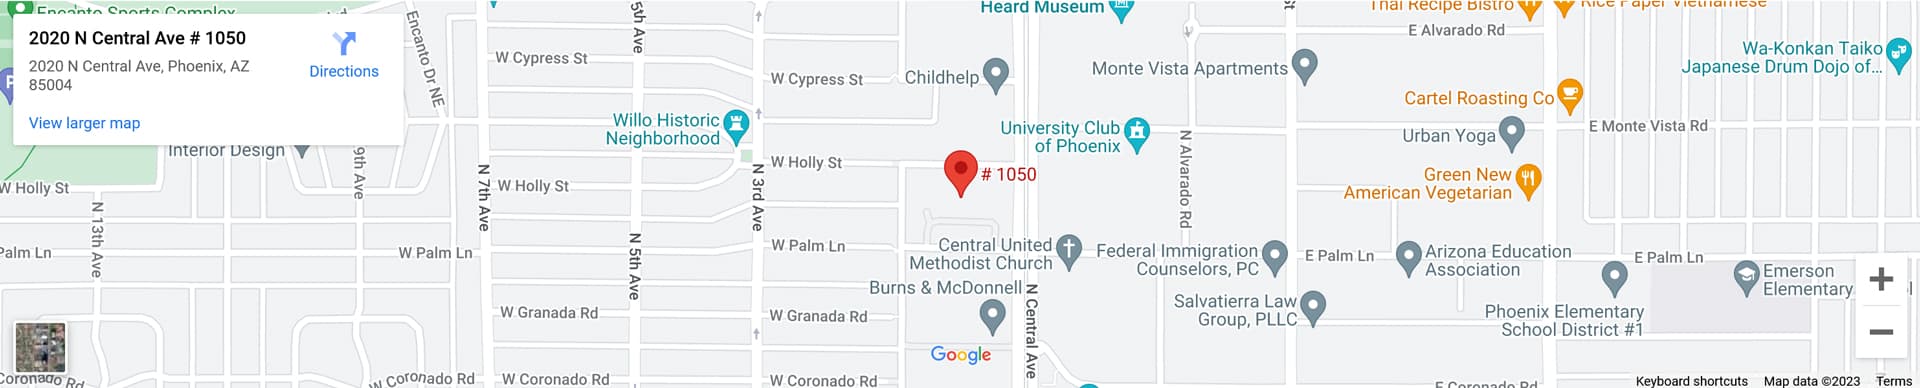
1099 Health Insurance is headquartered at 2020 N Central Ave in Phoenix. The team works with self-employed clients across the whole state, not just the Phoenix area. This includes people in Tucson, Mesa, Chandler, Scottsdale, Gilbert, Glendale, and every small town in between. Being based in Arizona means the team understands local carrier options and Arizona-specific costs, not just national averages.
What Happens After You Request a Quote
A lot of people put off getting a quote because they’re not sure what to expect. Here’s the actual process:
- You fill out a short form or call, and share basic details like your age, income estimate, and household size.
- A licensed advocate reviews ACA marketplace, private, and other plan options based on your situation.
- You get a side-by-side comparison, in plain language, not just a list of plan names and prices.
- You choose the plan that fits, and the advocate helps you enroll.
No pressure, and no cost to you for the help.
What Makes Arizona Different From Other States?
Health insurance rules are not the same everywhere. A few things make Arizona its own case:
- No state exchange. You always shop through HealthCare.gov, not a separate Arizona website.
- A large gig and contractor workforce. Arizona’s real estate agents, rideshare drivers, travel nurses, and contractors make up a big share of the self-employed population, and many carriers design plans with these jobs in mind.
- Wide cost differences by county. Premiums can vary depending on where in Arizona you live, even for the same plan type.
- Year-round growth in self-employment. With self-employment up nearly 13% in just a few years, more Arizonans are shopping for individual coverage for the first time, often without knowing where to start.
How to Pick the Right Plan: A Simple Checklist
You don’t have to be an expert to choose well. Just work through these steps:
- Write down your yearly income estimate. This decides your subsidy, so a good estimate matters.
- List your doctors and medications. Make sure any plan you pick actually covers them.
- Compare the monthly premium and the deductible together. A cheap premium with a huge deductible isn’t always the better deal.
- Check if you qualify for a subsidy. Many self-employed people still do, even after the 2026 changes.
- Ask about all your options, not just one. ACA marketplace, private, and short-term plans all work differently.
- Talk to a licensed advocate, not just a website form, if your situation is at all complicated.
Frequently Asked Questions
What is the best health insurance for self-employed people in Arizona? It depends on your income, health needs, and budget. Most self-employed Arizonans do best with an ACA marketplace plan. It can include a subsidy. It also covers pre-existing conditions. 1099 Health Insurance compares marketplace and private options together. That way, you see which one really costs less for you.
How much does health insurance cost for self-employed people in Arizona in 2026? The average Arizona marketplace premium after subsidies is about $229 a month in 2026. Your real cost depends on your income, age, and plan choice. Getting a personalized quote is the only way to know your actual number.
Do self-employed people in Arizona still qualify for ACA subsidies in 2026? Many do. About 83% of Arizona marketplace enrollees still received a subsidy in 2026, even after extra pandemic-era subsidy help expired at the end of 2025.
Is it free to work with a health insurance broker like 1099 Health Insurance? Yes. Licensed brokers are usually paid a commission by the insurance company, not by you. So comparing your options with an agent typically costs nothing extra.
Can I deduct my health insurance if I’m self-employed? Often, yes, through the self-employed health insurance deduction. The exact amount depends on your situation, so it’s worth confirming with a tax professional.
What if I only need coverage for a few months? Short-term health insurance can cover a short gap. Think between jobs or contracts. It does not cover pre-existing conditions. It’s not meant to be a long-term plan.
Does Arizona have its own health insurance marketplace? No. Arizona uses the federal marketplace at HealthCare.gov rather than running its own state exchange.
Can I open a Health Savings Account (HSA) as a self-employed person? Yes, if you choose an ACA marketplace plan that qualifies as a high-deductible health plan. Money you contribute is tax-free, and so is money you spend on qualified medical costs.
Can I sign up for health insurance any time of year, or only during open enrollment? Usually, only during open enrollment. But some events change that. Starting a business, losing other coverage, or a similar life event can open a Special Enrollment Period. That lets you enroll outside the normal window.
Get Your Real Arizona Health Insurance Quote
Guessing at a health insurance plan can cost you thousands of dollars a year, in either direction. Get a free quote from 1099 Health Insurance. See your actual options for 2026. This agency has already helped thousands of self-employed Arizonans do the same thing. You can also read more reviews or check the FAQ page if you still have questions.
Sources Used for This Article
- HealthInsurance.org: Arizona Health Insurance Marketplace 2026 Guide
- Arizona Center for Economic Progress: Small Businesses and Self-Employed Workers Could Lose Affordable Health Insurance
- HealthCare.gov: Official ACA Marketplace
- IRS Publication 535: Business Expenses (Self-Employed Health Insurance Deduction)
This article is for general information only and isn’t tax or legal advice. Health insurance costs and subsidy eligibility depend on your personal income, age, and situation — get a personalized quote or talk to a licensed advisor for exact numbers.